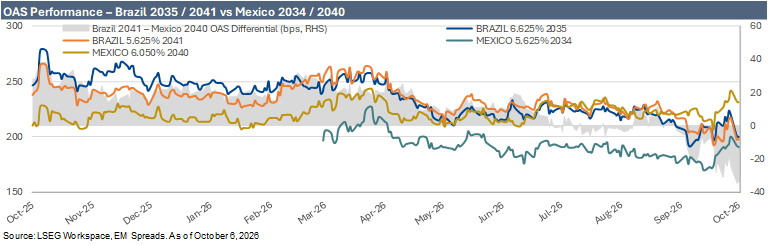
We move Brazil USD-denominated sovereign bonds to Neutral from Underweight following the first round and remain defensive on the curve. Our September Underweight combined valuation and event timing, and we identified the first round as the point to reassess it. Flávio Bolsonaro finished ahead of President Lula with 47.0% of valid votes against 45.2%. Roughly 8% went to eliminated candidates, mostly from the center and right of center. Right-of-center parties also strengthened their position in Congress, and the Liberal Party (PL) emerged as the largest party in both chambers, with 28 senators and 121 deputies. That gives a potential Bolsonaro administration a stronger legislative starting point for fiscal reform.
Neither of the re-entry conditions we set in September has been met. The Brazil 2035s trade at 199 bps of OAS, not around 230 bps, and no fiscal framework has been delivered. Those thresholds were set before the first-round result. The first round removes most of the event-risk rationale for the Underweight, but valuation remains restrictive. The Brazil 2035s at 199 bps offer only an 8 bp pickup to the Mexico 2034s at 191 bps, with 6.3 versus 5.8 years of duration. At the front end, the Brazil 2029s trade at 51 bps against 62 bps on the Mexico 2029s, with reported durations of 2.4 and 2.3 years. Further out, the Brazil 2041s trade 34 bps through the Mexico 2040s. The political signal is better; the valuation is worse. That leaves too little upside for Overweight and too little evidence for a broad sovereign Underweight.
Since September 17, Brazil has tightened 9 to 16 bps across the belly and long end while peers widened, with the Mexico 2034s 16 bps wider and the South Africa 2036s 15 bps wider. The clearest relative-value dislocation is the Brazil 2041/Mexico 2040 pair. The Brazil 2041s moved from 6 bps through the Mexico 2040s on September 17 to 34 bps through today, an additional 28 bps of relative tightening in three weeks, with reported durations of 9.2 and 8.6 years, respectively. The Brazil 2035/Mexico 2034 pair shows the same 28 bp compression, from a 36 bp Brazil premium on September 17 to 8 bps today, with durations of 6.3 and 5.8 years. Both Mexico bonds widened over the period, so two actual-bond pairs showing the same 28 bp move provide clear evidence of Brazil-specific repricing.