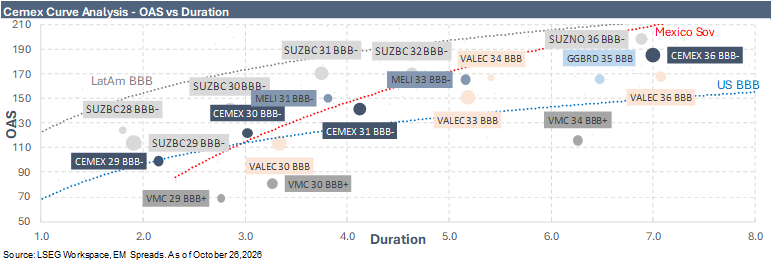
We upgrade Cemex (BBB-/BBB-) to Overweight from Neutral, maintain our Buy recommendation on the CEMEX 5.750% 2036 notes and add a Buy on the CEMEX 5.200% 2030 notes. We view the upgrade primarily as a valuation decision, since our previous Neutral reflected limited value outside the 2036s rather than concerns about the underlying credit. In 2Q26, we identified wider front-end spreads and further deleveraging without corresponding spread tightening as the conditions for an upgrade. Both are now substantially met. The 2030s have widened 31 bps since our 2Q26 report to 121 bps OAS, 18 bps more than the EM Corporate BBB Index, while the balance sheet has strengthened faster than we expected. We think the improvement in fundamentals, together with more attractive valuations in the intermediate curve, now supports an issuer-level Overweight.
Cemex has delivered the balance-sheet improvement we were looking for. Net leverage including perpetual notes declined to 1.8x from 2.1x in June, and net debt including perpetual notes is $535 million below December 2025, meeting management’s year-end reduction objective a quarter early. Net leverage excluding the $974 million of perpetual notes that rank behind the senior unsecured bonds reached 1.5x, while FFO to gross debt improved to 40.4% from 34.4%. The improvement was not primarily driven by one-off cash inflows. Net free cash flow excluding the Spanish carbon-capture grant and fixed-asset sale proceeds was ~$473 million in 3Q26, supporting our view that Cemex can preserve its stronger credit metrics through internally generated cash. Refinancing risk is low, with approximately $680 million of maturities through 2028 against $652 million of cash and a fully undrawn $3.0 billion committed revolver. S&P revised the outlook on its BBB- rating to Positive in September, joining Fitch. We view Positive outlooks from both agencies as a clear forward-looking signal of improving credit quality.