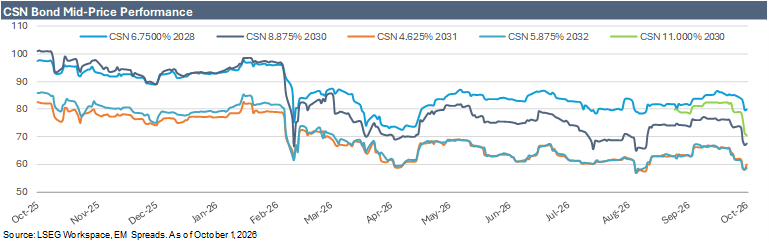
We maintain our Opportunistic Overweight recommendation on CSN, with lower conviction, and shift our preferred bond to the CSN Inova 11.000% 2030s from the CSN Resources 8.875% 2030s. The guidance cut does not create CSN’s liquidity problem. It weakens the principal operating buffer that was giving the company time to solve it. The reduction in 2026 production guidance and increase in C1 cash-cost guidance at CSN Mineração (CMIN) are credit negative. They make the thesis more dependent on the cement sale, working-capital release and continued refinancing access. The curve, however, has repriced by more than our fundamental view has changed. The Resources 2030s have widened 310 bps since our August report to 1,729 bps OAS. The Inova 2030s now trade at $71.3, 1,910 bps OAS and a 22.7% YTW. On a simple coupon-carry basis, they break even over 12 months at roughly $60.3. Default remains outside our base case over a 9 to 12 month horizon, and we think current levels compensate for the higher execution risk.
The bond switch reflects a material change in relative value since August. The Inova 2030 notes now offer 181 bps of additional OAS and 160 bps of additional YTW over the Resources 2030s, with 0.2 years less duration, and their dollar-price premium has narrowed to 3.1 points from 6.3 points when we last reviewed the curve on August 19. For investors assigning greater weight to an impairment scenario, the long end remains the defensive expression, and we prefer the CSN Resources 5.875% 2032s to the 4.625% 2031s. We continue to avoid the residual CSN Inova 6.750% 2028s.