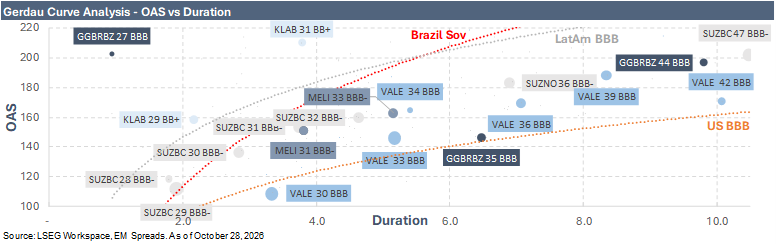
We maintain our Neutral recommendation on Gerdau (Baa2/BBB/BBB) and move our preferred bond to the GGBRBZ 7.250% 2044s from the 5.750% 2035s. Gerdau’s credit profile continued to improve in 3Q26, but we do not think current valuations justify moving above Neutral. Since our 2Q26 report, the 2035s have widened 8 bps to 145 bps OAS, less than half the 19 bps move in the EM BBB index, and now trade only 1 bp over the index against a one-year average differential of 12 bps. The 2044s have cheapened more, widening 31 bps to 195 bps, and the spread between the two bonds has increased to 50 bps from 27 bps. The maturity switch reflects that change in relative value rather than a different assessment of Gerdau’s credit.
Gerdau’s balance sheet strengthened further in 3Q26. Net leverage declined to 0.75x from 0.85x, and our sensitivity in the financial profile shows that a full year of North American EBITDA margins at 22% would lift net leverage only to about 0.93x and gross leverage to about 1.53x at unchanged debt. We consider those levels comfortable for a steel producer with Gerdau’s geographic mix, and they leave room to absorb a normalization in U.S. steel conditions without materially weakening the credit. Gross leverage of 1.24x and an LTM adjusted EBITDA margin of 17.8% also support further rating upside if sustained. Two of the three rating agencies have Positive outlooks, although we would view an upgrade as confirmation of credit strength already reflected in the financial statements rather than a reason to pay tighter spreads.