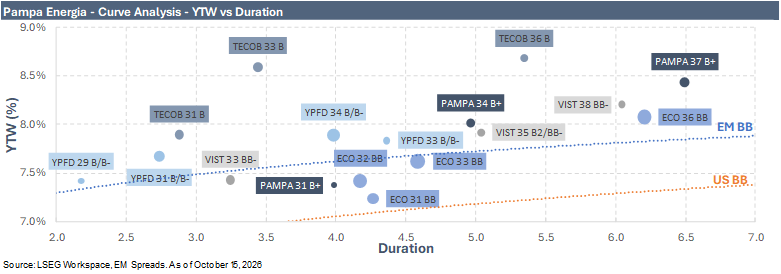
We initiate coverage of Pampa Energia with a Neutral recommendation, favoring the PAMPAR 7.875% notes due 2034 within its international bond curve. Pampa’s operating credit profile is improving, supported by rising oil production at Rincón de Aranda (RDA), stronger power generation profitability and manageable leverage. However, we expect much of the resulting cash-flow improvement to be absorbed by a second investment cycle rather than translated into meaningful deleveraging over our 9–12-month horizon. The timing is critical. RDA’s next production increase depends on infrastructure expected in 2027, while existing oil hedges constrain near-term participation in higher crude prices and Fértil Pampa introduces substantial funding requirements before contributing earnings. At 319 bps of OAS and an 8.01% yield to worst, the 2034s offer the most attractive balance of carry and duration within Pampa’s curve, particularly relative to the richer 2031s. Nevertheless, their 7 bps spread premium to Vista’s comparable 2035s provides limited compensation for Pampa’s less favorable near-term cash-flow trajectory and uncertainty surrounding Fértil Pampa’s financing, constraining the case for an outright Overweight.
LTM adjusted EBITDA excluding equity-accounted affiliates reached US$957 million in 2Q26, with net leverage of 1.38x and gross leverage of 2.72x. Liquidity stood at US$1.28 billion, equivalent to 2.3x cumulative scheduled principal maturities through 2029, with no international bond maturity until 2031. Cash generation remains the constraint. LTM free operating cash flow after interest and leases was negative US$616 million, reflecting elevated capital expenditures, working-capital requirements and derivative settlements. However, adjusted EBITDA excluding affiliates less cash capex and interest improved from negative US$424 million in 2025 to negative US$238 million LTM, including a US$27 million surplus before cash taxes and other adjustments in 2Q26. Pampa is moving closer to funding its existing investment program from operating earnings, but has yet to generate sustainable positive free cash flow.