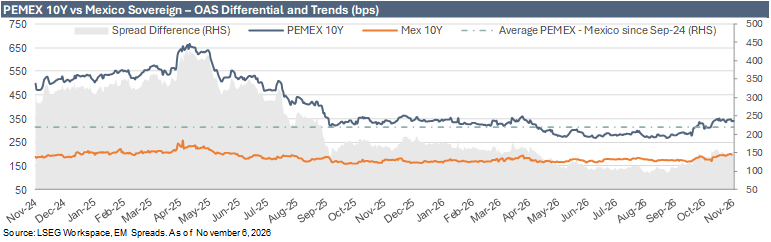
We maintain our Overweight recommendation on PEMEX (B1/BBB/BB+), keep the 6.625% 2035s as our core position and the 7.690% 2050s for investors able to absorb more duration, and add the 6.700% 2032s as our preferred shorter-duration alternative. The issuer call is unchanged, but we think it is a different Overweight from the one in our 2Q26 report. In that report, valuation was the binding constraint, with most of the curve trading within 25 bps of its one-year tights, and the case rested on carry and a lighter maturity profile. Relative to the 2Q26 reference levels in our accompanying exhibit, PEMEX bonds now trade 56 to 93 bps wider. That restores compensation and moves the constraint to fundamentals, where cash generation before government transfers has not improved on an LTM basis and the proposed 2027 federal transfer is sized to financial maturities rather than to PEMEX’s broader funding needs. Adding the 2032s is a valuation decision, reflecting a curve that now offers better compensation for extending duration through the 2032s before flattening considerably.
The progress that matters most for bondholders is in refinancing risk. Short-term debt has halved over the past year to US$11.41 billion, and available liquidity of US$14.54 billion, including undrawn committed facilities, now covers it 1.27x, against 1.00x in our 2Q26 report. Gross leverage fell to 3.3x from 4.0x, net leverage to 2.8x from 3.6x, and EBITDA interest coverage rose to 3.07x from a restated 2.49x. We would not read these ratios as standalone deleveraging. Much of the LTM EBITDA gain reflects a weak 3Q25 dropping out of the calculation, and the dollar decline in debt came from currency translation, while financial debt rose in peso terms. The higher cash balance was also helped by US$1.0 billion of additional revolver drawings and about US$1.75 billion raised through derivative strategies. In our view, headline leverage also flatters PEMEX against peers, because EBITDA is measured before the Welfare Oil Duty, a recurring fiscal charge equal to roughly 46% of quarterly EBITDA.