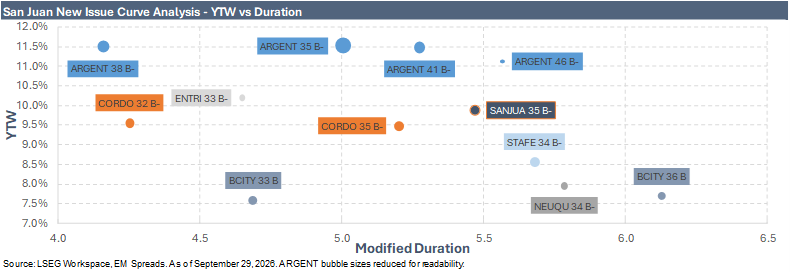
We initiate coverage of the Province of San Juan with an Overweight recommendation on the USD600mn 9.55% senior unsecured notes due October 2035, with an entry level of at least 50 bps over Córdoba 2035. The bond priced on September 24 at $98.234 to yield 9.875%, about 54 bps over Córdoba 2035 on September 28 levels. Córdoba 2035 has since widened to 9.482% YTW and 481 bps OAS from 9.338% and 466 bps, so our 50 bps entry now corresponds to a SANJUA yield near 9.98% and a price near $97.66. We do not treat the 39 bps pickup implied by the frozen reoffer yield as a current valuation. If the bond opens with full pass-through of Córdoba’s move, near 10.02% and $97.47, the original concession would be restored. If it opens near reoffer, we would hold existing positions but not add.
San Juan is not a top-tier provincial credit on current metrics. Our proprietary provincial framework ranks it 9th of 15 provinces, reflecting the post-issuance increase in leverage and limited provincial tax revenue. The Overweight rests on credit resilience. We think the province can carry the larger debt burden through the mining investment cycle without relying on the copper projects to generate material new revenues before 2033.
San Juan’s structural ratios deteriorate materially after the issue. Pro-forma debt reaches 9.7% of provincial gross geographic product (PBG) and 46.5% of revenue, while provincial tax revenue is only 12.6% of total revenue. Those metrics compare poorly with Córdoba, Santa Fe and Neuquén and justify a clear spread premium. At the same time, the new bond adds USD57.3mn of annual coupon expense through 2032, recent fiscal results remain positive and the province entered the transaction with substantial liquidity. We estimate total 2027 debt service, including existing local and multilateral obligations plus the new SANJUA coupon, at approximately USD86mn. The USD168.4mn of liquidity disclosed in May 2026 is close to 2.0x that amount before considering fiscal resources generated during the year. Most of that liquidity is peso-denominated, so the strength of the buffer still depends on national FX policy and the province’s ability to convert local-currency resources into dollars. That exposure makes the 2027 presidential election cycle directly relevant to the credit even if provincial fiscal performance remains strong.
Debt-service capacity remains credible under a deliberately conservative stress. If San Juan’s 2025 current fiscal balance of Ps341.2bn were held flat in nominal pesos through 2032 while the peso followed the depreciation assumptions used in the prospectus debt schedule, the resulting amount would still equal roughly 2.0x estimated annual pro-forma debt service in 2027 and about 1.5x in 2032. This is not a forecast. It is an EM Spreads stress test designed to assess whether the province can service debt through the capex period without assuming revenue growth from the new mining pipeline. The 1H26 current balance reached Ps212.5bn, providing further evidence that recurring fiscal capacity remained intact at the time of issuance.