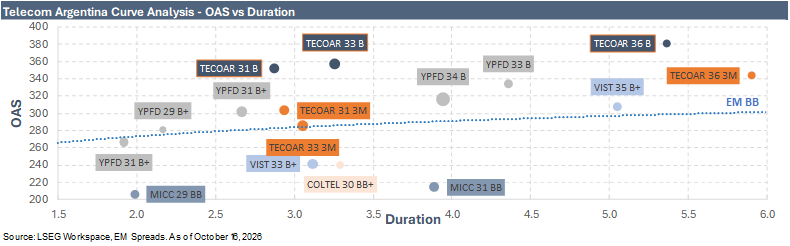
We maintain Neutral on Telecom Argentina (B2/B/B-) following its acceptance of Metrotel’s US$450 million offer for the customers and assets it must divest under the remedies imposed on its acquisition of Telefónica Móviles Argentina (TMA). The agreement is moderately credit positive. It removes a significant regulatory obstacle and brings Telecom closer to integrating the two businesses. However, the US$450 million is not equivalent to asset-sale proceeds. It includes guaranteed infrastructure-service payments over five years, with no disclosed breakdown between the two components. The immediate benefit to liquidity and leverage is therefore uncertain. At the bond level, we move the TECOAR 8.500% 2036s to Neutral from Overweight and maintain Neutral on the 2031s and 2033s. We now prefer the 9.250% 2033s.
Our August preference for the 2036s, outlined in Telecom Argentina 2Q26: Stronger Credit, Upside Gets Selective, was based on a roughly 50 bps OAS premium over the 2033s and more favorable call-price protection. That premium has narrowed to 24 bps, leaving insufficient compensation for 2.1 additional years of duration, particularly with Argentine sovereign risk still elevated. The 2033s offer a better trade-off. They provide 35 bps of additional Z-spread and 33 bps of yield over the 2031s for just 0.4 additional years of duration, while trading below their May 2028 call price. However, at 357 bps OAS, they are already 27 bps inside their one-year average and offer less than their one-year average premium over EM BB. We prefer the 2033s within the curve, but do not see enough value to upgrade them from Neutral.