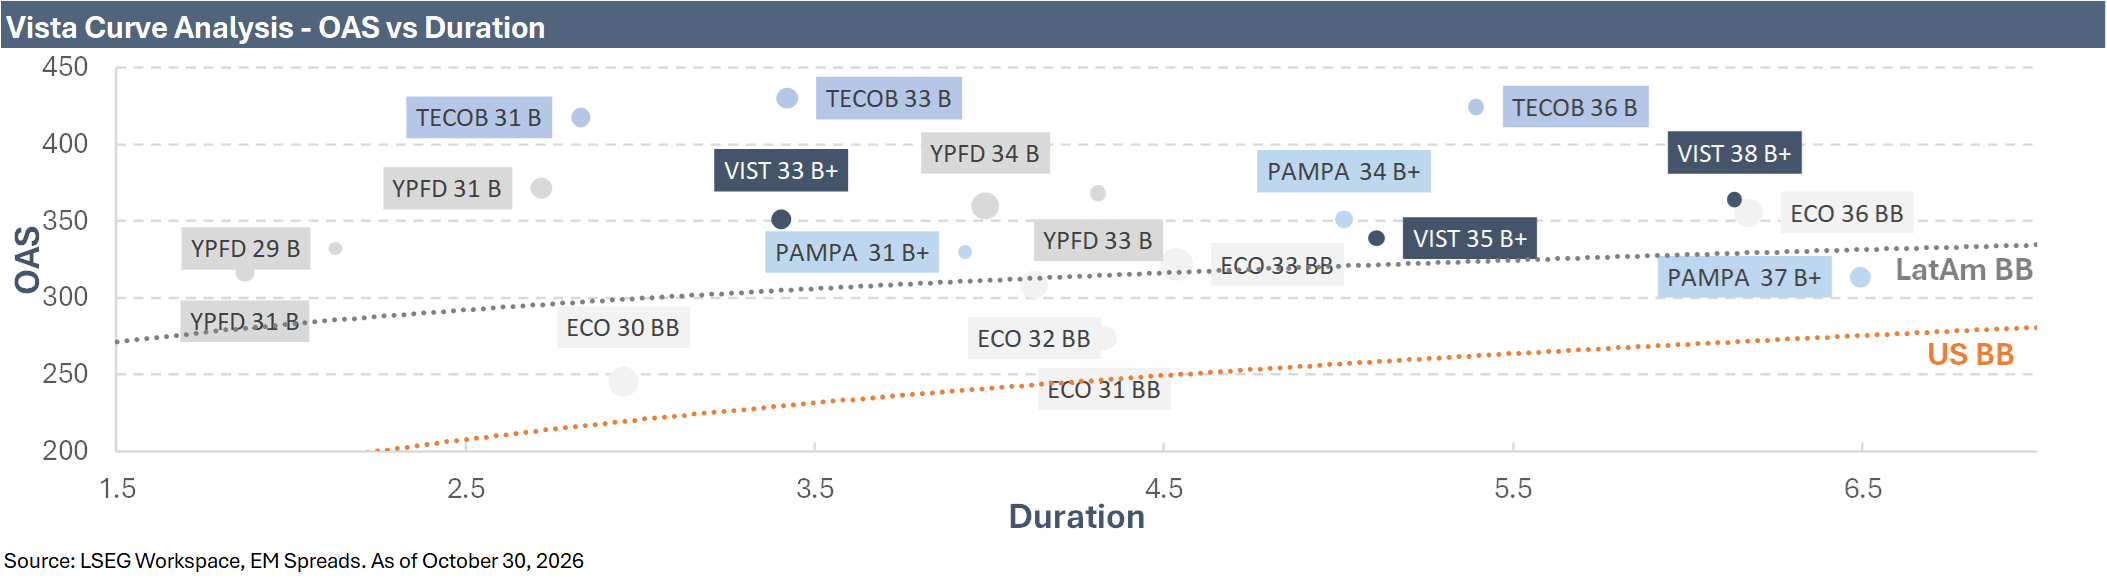
We maintain our Overweight recommendation on Vista Energy (B2/BB-) and move our preferred curve expression to the VISTAA 8.500% 2033 notes from the VISTAA 7.875% 2038 notes. The rationale for Overweight has changed since our 2Q26 report. At that time, the recommendation rested on a credit deleveraging faster than its curve was repricing, with the 2038s the only bond offering a meaningful OAS concession. Since then, Vista has delivered substantial deleveraging, with net leverage declining to 1.16x, while its bonds have widened 88–148 bps alongside a much sharper sovereign repricing. We think the issuer call now rests on valuation as much as on credit, and the bond switch reflects the changing distribution of value across the curve. The 2033s, which we did not favor for new money in our 2Q26 report, now trade 12 bps wide of the 2035s with 1.7 years less duration. With Argentina sovereign spreads at their widest level of the past year, we prefer to take Vista exposure at the shortest duration on its curve.
The credit basis for Overweight is stronger than in our 2Q26 report, but how the deleveraging was achieved matters for bondholders. Net leverage declined to 1.16x from 1.45x in 2Q26 and 1.87x a year earlier, while EBITDA interest coverage reached 8.20x. The improvement came primarily from EBITDA growth and cash accumulation rather than lower borrowings. Gross debt was broadly stable during the quarter and increased after quarter-end with the 2038 tap and additional short-term bank financing. We therefore expect further progress toward management’s approximately 1.0x year-end leverage target to depend more on earnings growth and cash retention than on gross debt repayment, leaving the trajectory sensitive to oil prices. Management estimates that a $1/bbl change in oil prices affects annual EBITDA by $45 million to $50 million, while its 2027 plan assumes $80/bbl Brent and approximately $1.9 billion of capex. LTM free operating cash flow increased to $662 million from $289 million in 2Q26. In our view, this provides stronger evidence that the enlarged asset base can fund its own development, even though quarterly cash conversion weakened as working capital reversed.