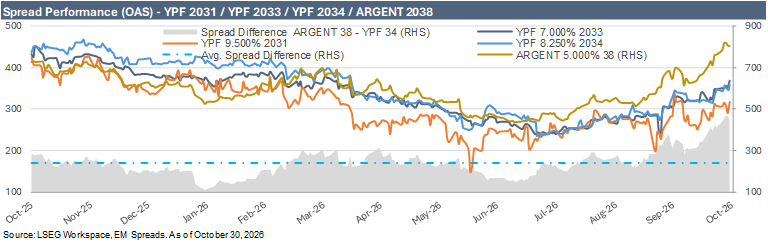
We maintain our Neutral recommendation on YPF (B1/B/B-) and reaffirm our bond-level Overweight on the 7.550% 2035s. We also replace the 8.250% 2034s with the 8.750% 2031s as our shorter-duration alternative. In our 2Q26 report, valuation was the principal constraint, with the curve trading close to its 1Y lows following a rapid re-rating. The 2033s and 2034s have since widened 113 bps and 103 bps against 42 bps for the EM BB index, removing much of the richness we flagged at the time. The belly is no longer expensive, although its historical relationship with BB credit does not suggest exceptional value either. The more important constraints are now Argentina’s deteriorating sovereign valuations and YPF’s approaching period of negative FCF and renewed borrowing ahead of the October 2027 election. We therefore maintain Neutral on credit and country-risk grounds rather than primarily on valuation. Within the curve, we continue to favor the 2035s, whose relative spread concession offers a more compelling entry than the issuer’s broader valuation.
YPF enters its next investment phase with net leverage at 0.81x, providing considerable capacity to absorb higher capital spending. For bondholders, the question is how much of that capacity the company will use. We expect cumulative FCF before M&A to turn negative over the four quarters to 3Q27 and net leverage to increase modestly. With YPF Luz consolidated, however, we still expect leverage below 1.0x at year-end, while VMOS exports beginning in March 2027 should support cash generation as production increases. Provided the additional investment delivers higher sustainable earnings, we would not view the resulting re-leveraging as a deterioration in underlying credit quality. The more immediate implication is additional debt supply, with the April 2027 investment plan expected to clarify the size of the funding requirement. The September tender left approximately $1.33 billion of 2027 maturities ahead of the October election, and we expect YPF to return to the debt markets before the vote. Argentina LNG adds a separate uncertainty. Management is targeting FID for November 26, but YPF’s equity commitment, funding schedule and potential recourse remain undefined. The credit has the balance-sheet capacity to support additional investment. The challenge is securing that funding on acceptable terms as the election approaches.